2027 Paying for an Online BA in Psychology - Mental Health: A Prior Student Loan Balance
Audited and Verified:
Our Editorial and Data Verification Process
Research.com uses government datasets, official education statistics and primary institutional information to support its career and degree guides. Our review process checks factual accuracy, occupational definitions, source dates and the requirements associated with the credentials discussed.
How This Article Was Fact-Checked
Our editorial team verifies salary estimates, employment projections, education requirements and program information against original data providers and official organizations. Salary figures are checked against the relevant occupational definitions and reporting periods. Information about licensure, accreditation and required in-person training is reviewed separately.
Fact-checked and verified on:

Co-Founder and Chief Data Scientist
An existing student loan balance does not automatically prevent you from financing an online BA in psychology with a mental health focus. It does, however, change the calculation: your loan status, remaining aid eligibility, transfer credits, and likely career path all affect whether borrowing more makes sense.
This guide is for returning students who want to finish a degree without mistaking admission for affordable completion. You'll learn how to check federal aid eligibility, estimate the cost of credits still needed, and weigh the degree against the qualifications required for your intended mental health role.
Key Things You Should Know
- An existing loan balance alone does not bar federal student aid; default, remaining borrowing limits, enrollment, and other eligibility rules matter.
- Federal Student Aid lists standard aggregate Direct Loan limits of $31,000 for dependent undergraduates and $57,500 for independent undergraduates, with exceptions and separate annual limits.
- Compare the cost of credits that actually satisfy your degree with the pay and credentials required for your target job; a psychology BA does not qualify you to provide therapy.
How Can You Pay for an Online Psychology Bachelor's Degree With Existing Student Loans?
Start with what you already owe, then price only the education you still need. An online BA is worth financing when its remaining cost is manageable and it advances a specific goal - not simply because another loan is available. Request your federal loan history through your Federal Student Aid account, check any private-loan statements, and identify each loan's balance, status, interest rate, and required payment.
Then obtain a written transfer evaluation and degree audit from each prospective school. Accepted credits can count as electives without satisfying general education or psychology-major requirements; that difference can add terms and borrowing. Compare the resulting cost with lower-cost online psychology study pathways, using each school's actual tuition, fees, credit requirements, and course schedule rather than its advertised price per credit.
The most useful financing sequence is to reduce the bill before deciding how to borrow:
- Complete the FAFSA for the applicable academic year and ask each school for an aid offer based on your expected enrollment.
- Ask whether transfer awards, grants, scholarships, employer assistance, or a payment plan can reduce the amount financed.
- Calculate the gap after aid, including books, technology, and any required in-person experience.
- Compare the projected payment on new borrowing with your existing payments and a conservative estimate of earnings in your target role.
Check your servicer before assuming current payments will stop when classes begin. Eligible federal loans may qualify for in-school deferment when you enroll at least half time, but interest can still accrue, particularly on unsubsidized loans. Private lenders set their own terms. A lower monthly payment during school is not the same as a lower total cost.
Can You Get Federal Student Aid With a Previous Student Loan Balance?
Usually, yes. Owing on a previous student loan is different from being in default on a federal student loan. A borrower who remains otherwise eligible can receive federal aid while repaying earlier loans, subject to the school's participation, satisfactory academic progress, enrollment rules, and applicable grant and loan limits. An unresolved federal loan default generally blocks additional federal aid until eligibility is restored under the applicable rules.
Direct Loan limits deserve particular attention if you borrowed for earlier undergraduate study. Federal Student Aid lists standard aggregate limits of $31,000 for dependent undergraduates and $57,500 for independent undergraduates; some dependent students whose parents cannot obtain a PLUS loan can qualify for higher unsubsidized limits. Annual limits also vary by year in school and dependency status. Ask the financial aid office to assess your record rather than assuming the aggregate ceiling equals the amount you can borrow next term.
Pell Grant eligibility is a separate determination. It depends on the applicable FAFSA calculation, enrollment, cost of attendance, and other rules, including lifetime eligibility; a loan balance neither creates nor eliminates a Pell Grant by itself. If licensed counseling is your eventual goal, preserve room in your financial plan for that distinct training route: compare mental health counseling education costs after aid before using all available resources on the BA.
How Much Does an Online Bachelor's Degree in Psychology Cost?
There is no reliable single price for an online psychology BA. Schools charge differently, and a returning student's total depends heavily on the credits still required. The comparison below shows which charges to request in writing; it does not assume that any school offers a particular price or aid award.
| Cost component | What to verify | Why prior borrowing matters |
| Remaining tuition | Credits that satisfy requirements × the applicable per-credit rate, or the school's term-based charge | Unused electives may leave more credits to finance than expected |
| Required fees and materials | Online, technology, course, books, and software charges | These can widen the gap after grants and employer assistance |
| Applied experience | Whether a placement, campus visit, or supervised activity is required and who arranges it | Travel or reduced work hours may create costs beyond tuition |
| Time to completion | Course rotation, prerequisites, residency credits, and part-time availability | Extra terms can increase costs while older loans continue accruing interest |
Ask for an estimated cost through graduation based on your degree audit, not a full-program sticker price that assumes you are starting from scratch. If your goal is specifically substance-use services, compare the requirements and total remaining cost of inexpensive undergraduate substance use counseling degree choices; check your state's credential rules before treating any program as a route to counseling work.
Choose an institution with recognized institutional accreditation and confirm that it covers the institution awarding the degree. Check the accreditor through the U.S. Department of Education or the Council for Higher Education Accreditation, and ask the school whether the online BA is offered by that accredited institution. This helps you evaluate academic legitimacy and can matter for federal aid, transfer, and later study; it does not guarantee that another school will accept every credit.
Do not look for APA accreditation of an ordinary psychology BA. APA accreditation applies to specified professional psychology training programs, not general undergraduate psychology majors. Likewise, a "mental health" or "addictions" concentration is an academic focus, not a professional license. A bachelor's-level addiction psychology program guide can help identify options, but verify each institution's accreditation, exact degree title, and any concentration on its current program page.
Most psychology bachelor's programs combine foundational coursework with research methods and statistics. A mental health focus may add study of psychopathology, development, substance use, prevention, and service systems. These subjects help students evaluate evidence and understand support settings; learning about diagnosis or treatment in class does not authorize a graduate to diagnose or treat people.
For a student with prior loans, curriculum fit is also a cost issue. Ask whether earlier statistics and psychology courses satisfy major requirements, whether advanced courses have prerequisites, and whether a required internship is available remotely or near home. If your interest has shifted from mental health services toward justice-system research or support, accelerated undergraduate forensic psychology study may offer a different curricular comparison. A forensic focus, however, does not confer investigative or clinical authority.
Online psychology BA admission typically involves proof of prior schooling and transcripts, but transfer GPA rules, application materials, and admission to the major vary. Ask the registrar or transfer office for a course-by-course evaluation and the psychology department for approval of major equivalencies. The financial aid office should separately review aid eligibility and satisfactory academic progress, especially if you previously attempted many credits or left school without completing them.
If you already have a bachelor's degree, pause before applying for a second one. A target graduate program may accept your existing major with a few psychology or statistics prerequisites instead. Compare those requirements and the cost of cost-conscious options for a psychology master's before paying for another BA. A general psychology master's may support research or nonclinical work, but it should not be assumed to qualify you for counseling licensure.
Time to graduation depends on the approved degree audit, course sequencing, and how many classes you can sustain each term - not just the advertised length of an online program. A school may accept substantial prior credit while still requiring upper-level psychology courses in a particular order or a minimum number of credits earned there.
Accelerated terms can shorten the calendar without reducing the coursework. When comparing intensive online psychology program formats, ask for a term-by-term plan showing when required courses actually run. If you work or provide care for others, check weekly deadlines, live sessions, group work, and placement hours before choosing a pace. Finishing faster helps financially only if it avoids extra terms without causing withdrawals, repeated classes, or lost income you cannot absorb.
A psychology BA can support applications for nonclinical roles such as behavioral-health program assistant, intake or referral coordinator, victim-services assistant, and social or human services assistant. Duties may include documenting contacts, connecting people with services, supporting programs, or assisting a supervised team. Employers may also require relevant experience, background checks, specific training, or another credential.
Look at actual job postings in your area before borrowing for the degree. If they emphasize experience, an approved internship, community-service work, or research assistance may strengthen your application more than additional electives. For a role that requires graduate education, plan the full route - including prerequisites and online psychology master's completion planning - rather than assuming the BA is the final expense. A general psychology master's still does not substitute for a qualifying clinical degree.
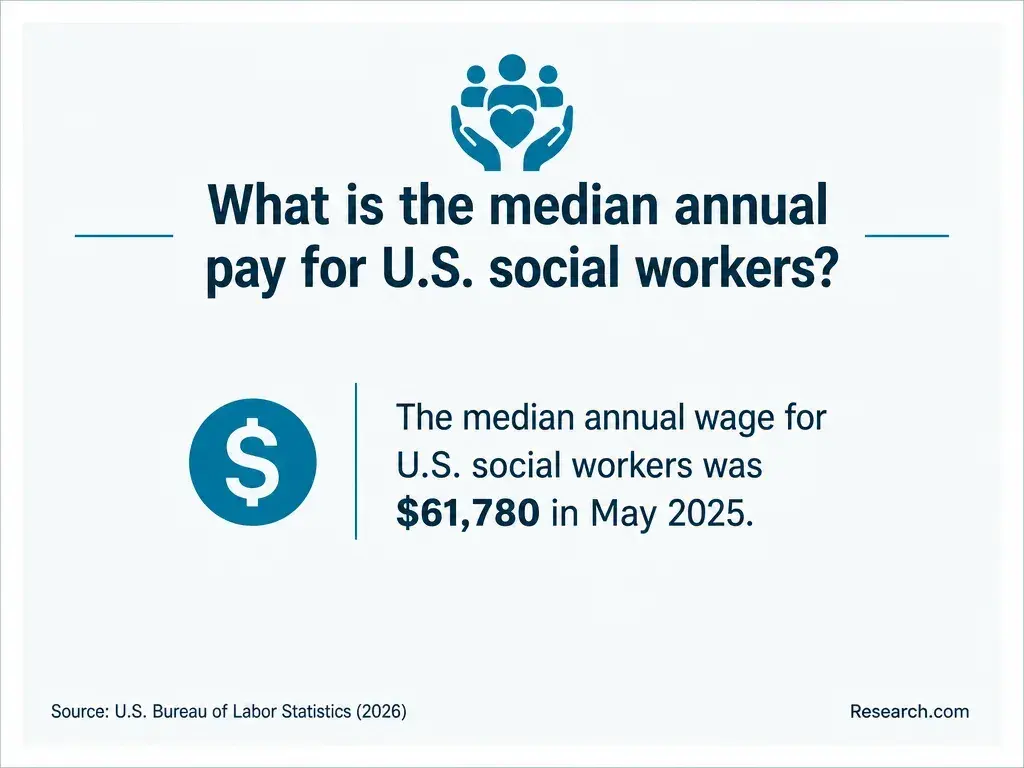
There is no dependable salary figure for everyone with a psychology BA. Pay attaches to an occupation, employer, location, and experience level - not to the degree name alone. The U.S. Bureau of Labor Statistics reported a May 2024 median annual wage of $45,120 for social and human service assistants, an occupation that can include mental-health-related support work. That occupation-wide midpoint is not a starting salary or an outcome for graduates of a particular online program.
For a borrowing decision, compare local postings for jobs you could qualify for soon after graduation with postings requiring additional credentials. Do not use salary outlook for forensic psychology master's graduates as an earnings estimate for a mental health-focused BA: it concerns different education and potentially different jobs. Ask a prospective school for documented outcomes specific to its graduates, including how many responded, rather than relying on an undifferentiated salary claim.
Do You Need Graduate School or Licensure for Mental Health Careers?
For many support and coordination jobs, graduate school is not the immediate requirement; employer training, relevant experience, or a state-specific support credential may matter more. Providing psychotherapy, independently diagnosing conditions, or practicing as a licensed psychologist generally requires a distinct qualifying education and supervised licensure pathway. Requirements vary by profession and state, so check the licensing board for the occupation and location you intend to pursue.
If your goal is licensed counseling, investigate qualifying counseling programs rather than assuming a psychology BA concentration or general psychology MS meets that goal. Compare total tuition, placement arrangements, and state eligibility - not speed alone - when reviewing faster-paced online mental health counseling master's study. If your immediate goal is a nonclinical support job, a less expensive degree-completion route, targeted training, or relevant employment may be a better next investment than borrowing for graduate school.
Other Things You Should Know About Psychology
The FAFSA does not use your credit score to determine eligibility for undergraduate Direct Subsidized or Unsubsidized Loans. Other eligibility rules still apply, and private lenders generally assess credit.
Federal student aid is awarded for eligible educational expenses in your current enrollment, not as a way to refinance earlier education debt. Ask your servicer about repayment options for existing loans.
It can complicate enrollment or access to records. Contact the former school about its current transcript and balance policies, then ask the new school which documents it needs to evaluate your credits.
Compare the terms carefully. Refinancing federal loans with a private lender can permanently remove federal repayment, deferment, and forgiveness protections; a lower advertised rate does not capture that trade-off.
- Annual and Aggregate Loan Limits | 2024-2025 Federal Student Aid Handbook https://fsapartners.ed.gov/knowledge-center/fsa-handbook/2024-2025/vol8/ch4-annual-and-aggregate-loan-limits
- Federal Versus Private Loans | studentaid.gov https://studentaid.gov/understand-aid/types/loans/federal-vs-private
- What Financial Aid Offers Don't Tell You About the Cost of College | U.S. GAO https://www.gao.gov/blog/what-financial-aid-offers-dont-tell-you-about-cost-college
- Compliance Challenges for Title IV Eligibility in Online and Hybrid Programs - UPCEA https://upcea.edu/news/government-affairs/compliance-challenges-for-title-iv-eligibility-in-online-and-hybrid-programs/
- Consequences of Default and Actions to Take | uccs.edu https://finaid.uccs.edu/types-of-aid/educational-loans/default15
- What to Know About Your College's Net Price Calculator | Campus https://campus.edu/blog/financial-aid/your-colleges-net-price-calculator
- Financial Aid | Satisfactory Academic Progress Policy | Western Dakota Technical College https://www.wdt.edu/paying-for-school/financial-aid/satisfactory-academic-progress/