2027 FAFSA vs Private Loans for Addiction Psychology Degree Master's Students

Co-Founder and Chief Data Scientist
Imagine a career changer eager to pursue a master's in Addiction Psychology but overwhelmed by financing options. Nearly 60% of graduate addiction counseling students rely on loans to fund their education, facing tough choices between federal FAFSA loans with fixed protections and private loans that may offer higher limits but come with less security.
These students must navigate income-driven repayment, variable interest rates, and eligibility nuances while considering future career stability. This article breaks down the key differences between FAFSA and private loans, highlighting eligibility, repayment, and risk to guide Addiction Psychology master's students toward financially sound borrowing decisions.
Key Benefits of Comparing FAFSA vs Private Loans for Addiction Psychology Degree Master's Students
- FAFSA federal loans offer broader eligibility and income-driven repayment plans, providing forgiveness options that private loans typically lack, aiding addiction psychology master's students in managing long-term debt more effectively.
- Private loans often require a strong credit history and may carry higher interest rates, increasing total borrowing costs and financial risk for students without established credit or stable income.
- Understanding these differences helps students prioritize scholarships and FAFSA aid first, using private loans only after exhausting federal options to safeguard post-graduation financial stability in addiction psychology careers.
What is the difference between FAFSA and private loans for addiction psychology master's students?
Prospective addiction psychology master's students face important choices when financing their education. Comparing federal FAFSA loans versus private loans helps clarify the protections and limitations of each, providing a clearer path toward responsible borrowing. Below are key points to consider about how these options differ:
- FAFSA Is a Financial Aid Application: The Free Application for Federal Student Aid (FAFSA) is not a loan but a form used to determine eligibility for federal aid programs. For addiction psychology graduate students, completing FAFSA unlocks federal options such as Direct Unsubsidized Loans and Graduate PLUS Loans.
- Private Loans Are Issued by Non-Government Lenders: Private loans come from banks, credit unions, or online lenders. These rely on creditworthiness rather than federal criteria and are regulated by contract law, making their terms less flexible than federal loans.
- Interest Rates and Repayment Plans Differ: Federal loans offer fixed interest rates and a range of repayment plans including income-driven options and deferment. In contrast, private loans often have variable rates and limited repayment flexibility, increasing financial risk for students.
- Eligibility and Credit Requirements: Federal loans require FAFSA completion and enrollment but no credit check, while private loans usually mandate a credit check and sometimes a co-signer, which can be a barrier for students with limited credit history.
- Loan Forgiveness and Default Consequences: Federal loans may qualify for forgiveness programs relevant to addiction counseling careers; private loans generally do not, and defaults can severely damage credit scores.
Approximately 65% of graduate students rely on federal student loans, highlighting FAFSA's central role in funding addiction psychology degrees. This article will further explore repayment options and forgiveness programs for addiction psychology graduate loans, as well as total cost comparisons, scholarship alternatives, and refinancing strategies to help students make informed financial choices. Those looking for related financing information might also consider programs like affordable online MBA programs as part of their broader educational planning.
How does FAFSA eligibility work for addiction psychology master's degree candidates?
Prospective addiction psychology master's degree students must navigate specific federal aid eligibility requirements to maximize funding opportunities. Understanding how fafsa eligibility affects addiction psychology master's students is essential for successful application and planning. The following key points highlight the critical criteria and timelines involved.
- Citizenship and Residency Requirements: To qualify for federal aid, students must be U.S. citizens or eligible non-citizens with valid permanent residency. International applicants usually do not qualify for federal loans but can explore alternative institutional or private funding options.
- Enrollment Status and Impact on Aid: Full-time enrollment typically results in larger aid packages. Addiction psychology master's students must usually maintain at least half-time enrollment to retain federal loan eligibility, with part-time study often reducing available aid amounts.
- Satisfactory Academic Progress (SAP): Maintaining minimum GPA standards and completing a required percentage of attempted credits is mandatory to continue receiving federal financial aid. Falling behind on SAP can jeopardize funding access.
- Graduate Student Classification: Graduate-level addiction psychology students are automatically considered independent on the FAFSA, so parental income is excluded from calculations. This affects the Student Aid Index (SAI) and often results in different aid offers compared to undergraduate applicants.
- FAFSA Filing Timeline and Student Aid Index: The FAFSA application opens every October 1 for the upcoming academic year. The SAI replaces the Expected Family Contribution (EFC) and reflects the financial need of the student, influencing loan limits and grant eligibility for graduate applicants.
Over 70% of graduate students who submit FAFSA applications receive some federal aid, underscoring the importance of meeting fafsa requirements for graduate addiction psychology programs promptly. Students seeking additional financial options might consider scholarships or private loans cautiously, while also evaluating certificates I can get online to augment their qualifications and career prospects.
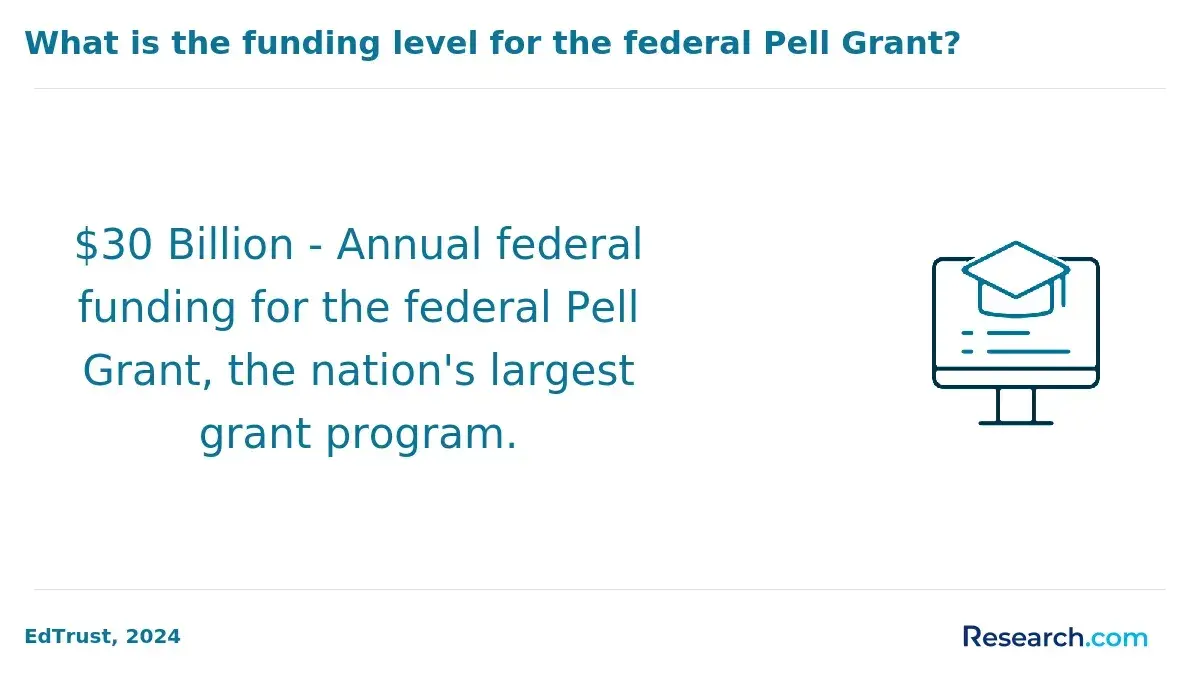
What federal loan types are available to addiction psychology graduate students through FAFSA?
Graduate students pursuing an addiction psychology master's degree often rely on federal loans through FAFSA to fund their education. Understanding the main loan options and their features can help manage costs effectively. The following points highlight key aspects of these federal loans:
- Direct Unsubsidized Loans: Available for up to $20,500 per year regardless of financial need, these loans accrue interest during enrollment at a fixed rate of 7.05% for the 2023-2024 academic year. They charge an origination fee of about 1.057%, with a total borrowing limit of $138,500 including undergraduate amounts.
- Graduate PLUS Loans: Designed to cover remaining tuition and expenses after other aid, Graduate PLUS Loans require a credit check. Their fixed interest rate is 8.05% for 2023-2024, and they carry a higher origination fee of approximately 4.228%. Unlike Direct Loans, these have no aggregate limit but are capped at the cost of attendance minus other aid.
- Income-Driven Repayment (IDR) Plans: These repayment options adjust monthly payments based on income, providing vital flexibility for graduates entering the addiction psychology field who might start with lower salaries.
- Public Service Loan Forgiveness (PSLF): Graduates employed in qualifying nonprofit or government roles in addiction psychology may become eligible for forgiveness of remaining loan balances after 120 payments made under an IDR plan.
- Deferment and Forbearance Options: Federal loans offer the ability to temporarily delay or reduce payments during financial difficulties or additional schooling, helping borrowers avoid default and protect credit.
A professional who transitioned careers by enrolling in an online addiction psychology master's program shared that navigating the loan process felt overwhelming at first. He recalled, "I wasn't sure which loans would best support my studies or how the repayment worked if I had to return to school or face financial setbacks."
After getting familiar with income-driven plans and deferment options, he felt more confident managing his debt alongside job changes. "Knowing there was flexibility in repayment gave me peace of mind during such a major life change," he explained, emphasizing that access to federal loan benefits made the educational pivot more achievable.
For students pursuing an addiction psychology master's degree, weighing the pros and cons of FAFSA-based federal aid is essential for managing the financial commitment. Below are key considerations to help navigate federal loan benefits and limitations:
- Fixed Interest Rates: Federal unsubsidized loans have stable, fixed interest rates that do not fluctuate, making it easier to plan your budget compared to private loans with variable rates.
- No Credit Check for Unsubsidized Loans: These loans don't require credit approval or co-signers, offering accessibility to applicants with limited credit history.
- Flexible Repayment Options: Income-driven and other adaptable repayment plans accommodate graduates entering addiction psychology careers with varying income levels.
- Loan Forgiveness Programs: Certain borrowers qualify for forgiveness, such as Public Service Loan Forgiveness, which is particularly relevant for clinical or community health roles.
- Borrowing Limits and Costs: Despite these advantages, federal loan caps may not cover all addiction psychology graduate expenses. Origination fees apply, and subsidized loans aren't available for graduate students, leading to accruing interest during study.
Institutional aid-assistantships, fellowships, and scholarships focused on addiction psychology-often reduce federal loan eligibility since schools integrate these into overall aid packages. According to the National Center for Education Statistics, about 60% of graduate students combine multiple funding sources. FAFSA-based federal aid might suffice when coupled with substantial institutional support and manageable living expenses, but many students turn to other options or private loans to bridge funding gaps.
Exploring options like online mental health counseling programs can also offer alternative or supplemental pathways.
For prospective master's students in Addiction Psychology considering private funding, knowing how private loans function helps in making informed financial decisions. The following points outline the crucial aspects of private student loans relevant to graduate borrowers.
- Lender Types: Private loans come from a diverse range of lenders, including national banks, credit unions, fintech companies, and occasionally programs affiliated with schools. Each offers distinct features, eligibility rules, and repayment options tailored for graduate education.
- Approval Criteria: Borrowers are assessed based on credit score thresholds, debt-to-income ratios, and employment stability. Addiction Psychology students with less-established credit histories can often improve approval chances and secure better terms by adding a co-signer with strong credit.
- Loan Process: The typical procedure involves submitting an application, completing a credit evaluation, and providing enrollment verification from the school. Once approved, the loan funds are sent directly to the educational institution to cover tuition and fees.
- Repayment and Deferment: Many private loans allow in-school deferment, enabling students to postpone payments while enrolled; however, interest usually accrues during this time. Terms such as interest rates and repayment periods vary greatly depending on the lender.
- Lender Comparison: Because loan conditions differ widely across providers, Addiction Psychology students should evaluate the offerings from at least three lenders, considering interest costs, fees, and flexibility before deciding.
A professional who completed her Addiction Psychology master's reflected on navigating private loans as both intimidating and necessary. She recalled the stress of assembling co-signer paperwork and comparing lender offers. "It felt overwhelming at first, especially balancing credit checks and waiting for approvals," she shared.
However, she noted that thorough research and patiently reviewing all terms ultimately led to a manageable loan that supported her through school. Her experience highlighted the importance of diligence and using a co-signer to access favorable financing options in a competitive lending environment.
For students pursuing a master's degree in Addiction Psychology, private loans can seem like a tempting option when other funding falls short. However, weighing their benefits against potential drawbacks is essential before committing. Below are several important considerations regarding private student loans:
- No Origination Fees and Flexible Rate Options: Many private lenders don't charge origination fees, reducing upfront costs. Borrowers often have the choice between fixed and variable interest rates, which can offer some flexibility depending on market trends and personal risk tolerance.
- Ability to Borrow Up to Full Cost of Attendance: Unlike federal loans that have set borrowing limits, private loans can cover the entire cost of tuition, fees, and living expenses when other aid is insufficient. This flexibility helps fill financial gaps that federal aid may not address.
- Potential for Rising Variable Rates: Variable interest rates often start lower than fixed rates but can increase significantly over time. This unpredictability can lead to higher monthly payments and financial pressure, particularly for graduates who begin their careers with modest incomes.
- Absence of Federal Protections and Forgiveness: Private loans lack access to federal forgiveness programs and income-driven repayment plans. For Addiction Psychology graduates typically earning less in entry-level roles, the absence of these safety nets can increase financial stress during repayment.
- Limited Hardship Support and Aggressive Collections: Compared to federal loans, private lenders offer fewer options for deferment or forbearance. Defaulting on private loans often triggers aggressive collection practices that can adversely affect credit and financial stability.
While private loans may provide necessary funding when federal aid is exhausted, they should be viewed as a last-resort option. Addiction Psychology students should carefully evaluate terms, consider long-term repayment capacity, and exhaust scholarships and federal loans before pursuing private borrowing.
Prospective addiction psychology master's students face important decisions about financing their education, particularly when choosing between federal and private student loans. Interest rates and repayment terms vary considerably, affecting the total cost of borrowing. Below are essential factors to consider when comparing these financing options.
- Federal Loan Rates Are Fixed and Predictable: Direct Unsubsidized Loans currently have fixed interest rates of approximately 7.54%, while Grad PLUS Loans carry slightly higher fixed rates around 8.05%. These rates are reset annually by the federal government but remain stable for the loan term, helping borrowers anticipate consistent monthly payments.
- Private Loan Rates Are Typically Variable and Market-Linked: Private lenders usually base their variable interest rates on benchmarks such as the Secured Overnight Financing Rate (SOFR) or the Prime Rate. These rates often start lower than federal loans but can fluctuate with market conditions, leading to uncertainty in overall repayment costs.
- Long-Term Cost Differences Can Be Significant: For example, borrowing $30,000 over 10 years at a fixed federal rate of 7.54% results in about $41,000 total repayment. A private loan beginning around 6.5% variable interest may initially offer lower monthly payments but could surpass federal totals if rates rise above 8% through the repayment period.
- Annual Federal Rate Updates Require Monitoring: Since federal rates change yearly, students should check StudentAid.gov regularly to access the latest Direct Unsubsidized and Grad PLUS loan rates before committing to borrowing.
- Private Loan Offers Depend on Individual Factors: Interest rates vary based on lender policies, borrower creditworthiness, and whether a co-signer is involved. Prospective borrowers should carefully research and compare lender terms to identify the best options and understand possible rate caps or adjustments.
Repayment plan options are a vital consideration for addiction psychology master's students as they plan how to manage educational debt. Selecting between FAFSA federal loans and private student loan repayment plans for addiction psychology master's students impacts financial flexibility and stress levels after graduation. Below is an outline of key distinctions in repayment choices, borrower protections, and practical effects on cash flow for graduates.
Important points include:
- Variety of Federal Repayment Plans: Federal loans offer multiple repayment options such as the standard, graduated, and extended plans alongside income-driven plans like IBR, SAVE, ICR, and PAYE. These income-based plans help borrowers align payments with earnings in early career stages, often reducing financial burdens significantly.
- Limited Private Loan Options: Private loan repayment typically involves choosing between fixed monthly payments or interest-only payments during school, lacking the adaptive income-driven alternatives found in federal loans. This limited flexibility can challenge budgeting after graduation when incomes may fluctuate.
- Deferment and Forbearance Availability: Federal loans provide deferment and forbearance, allowing temporary payment pauses during hardships. The COVID-19 pandemic revealed federal loan flexibility not always matched by private lenders, highlighting risks for borrowers relying on private credit during economic downturns.
- Impact on Financial Planning: Income-driven federal repayment plans support better financial planning by adjusting payments based on income, promoting long-term stability. Conversely, private loans with fixed repayment terms may increase default risk if borrowers face income shortfalls.
- Recent Trends: Over 70% of graduate borrowers now use income-driven federal repayment plans, underscoring their growing role in managing education debt in fields including addiction psychology.
For a comprehensive perspective, students may consider creating a comparison table outlining repayment flexibility between federal and private loans at various income levels specific to addiction psychology graduates. This helps visualize long-term effects and supports informed borrowing decisions.
Prospective students seeking financing guidance might also explore options in masters in psychology to better understand cost structures and reduce borrowing needs.
For master's students in addiction psychology, especially those considering the financing of their education, the Public Service Loan Forgiveness (PSLF) program offers a critical benefit but comes with specific eligibility requirements. Below are key points to understand about PSLF eligibility for Addiction Psychology graduates and its impact on federal versus private loans.
- PSLF Eligibility Requirements: Borrowers must make 120 qualifying monthly payments while enrolled in an income-driven repayment plan and maintain full-time employment with a qualifying employer, typically a government agency or a 501(c)(3) nonprofit. Private student loans are not eligible for PSLF under any circumstance.
- Common Qualifying Employers in Addiction Psychology: Many graduates work in nonprofits, government health programs, or public universities. Positions in state health departments, community mental health centers, and federally funded initiatives usually meet PSLF criteria.
- Career Paths Less Likely to Qualify: Those employed by private clinics, for-profit counseling centers, or companies outside public or nonprofit sectors generally will not benefit from PSLF eligibility.
- Importance of Federal Loans: Since private loans are excluded from PSLF, federal loans obtained through FAFSA represent the most strategic funding option for students targeting public service roles in addiction psychology, providing repayment protections and forgiveness opportunities.
- Utilizing Official Resources and Waivers: Prospective borrowers should consult the official PSLF Help Tool to verify current eligibility and monitor changes such as the recent PSLF waiver that temporarily expanded qualifying payment criteria.
Notably, fewer than 50,000 borrowers have successfully received PSLF forgiven loans, underscoring the importance of understanding requirements and employment status ahead of time. Awareness of these rules can influence financing choices, particularly when balancing scholarships, credit requirements, and refinancing options after graduation.
Master's students exploring financing options should also consider alternatives like scholarships and ensure they prioritize free money before federal loan options. Private loans may provide flexibility but carry greater risk and no PSLF eligibility. For those in addiction psychology, navigating these differences is essential to managing debt responsibly and optimizing post-graduate career outcomes.
For students seeking related creative fields, reviewing the online game design degree ranking offers insight into affordable program choices in other disciplines.
For prospective addiction psychology master's students exploring private loan options, credit history plays a vital role in determining eligibility and interest rates. Navigating the landscape between private and federal loans requires understanding key credit-related factors. Below are essential considerations to help guide applicants through financing choices.
- Minimum Credit Score Benchmarks: Private lenders typically expect a FICO score between 650 and 700 or higher. Many recent graduates entering addiction psychology programs may face challenges qualifying due to limited or thin credit histories.
- Co-Signer Impact and Risks: A co-signer with strong credit can enhance approval odds and secure better interest rates. However, co-signers take on full repayment responsibility if the borrower defaults. Release options allowing co-signers to exit after timely payments depend on lender policies and often require multiple years of consistent repayment.
- Federal Loan Credit Policies: Direct Unsubsidized Loans do not consider credit scores, offering accessible funding irrespective of credit history. Grad PLUS Loans undergo a softer adverse credit check excluding major negative marks, making eligibility easier than with private lenders.
- Credit-Building Strategies: Students should work to create or improve credit profiles before applying for private loans by opening secured credit cards, maintaining punctual payments on existing debts, and avoiding new borrowing in the months leading to enrollment.
Students pursuing a master's degree in Addiction Psychology must carefully evaluate their total cost of attendance (COA) to understand financing options. This includes comparing federal loan limits and private loan possibilities to cover educational expenses. Below are essential aspects to consider regarding COA and borrowing limits.
- Components of Cost of Attendance: Institutions calculate COA by combining tuition, mandatory fees, room and board, textbooks, transportation, and personal expenses, reflecting the estimated yearly cost for a student in an addiction psychology program.
- Federal Loan Limits: Graduate students may borrow up to $20,500 annually through Direct Unsubsidized Loans regardless of COA. However, Grad PLUS Loans can cover up to the entire COA minus any other financial aid awarded.
- Private Loan Certification: Private lenders usually verify the school-certified COA and may approve loans up to this verified amount, enabling students at higher-cost programs-such as private or out-of-state schools-to exceed federal borrowing limits if necessary.
- Average COA Ranges: Addiction psychology master's programs at public universities often cost between $30,000 and $40,000 per year, private institutions range from $45,000 to $60,000, while online programs typically fall lower but with considerable variation.
- Borrowing Implications: Taking out loans for the full COA through Grad PLUS or private financing increases debt after graduation. Prioritizing scholarships and federal loans with borrower protections is advisable before resorting to private loans, which may have higher interest rates and fewer safeguards.
What Graduates Say About Comparing FAFSA vs Private Loans for Their Addiction Psychology Master's Degree
- Kelsey: "Choosing FAFSA to fund my Addiction Psychology master's degree was a strategic decision because it offered lower interest rates and deferred repayment options, which minimized my financial stress during studies. The overall cost of the program was a significant investment, but it was worth it for the quality of education and clinical exposure I received. Completing this degree helped me secure a counseling position faster than I anticipated and gave me the confidence to pursue licensure and specialize in substance abuse treatment."
- Marco : "I opted for private loans to cover my Addiction Psychology master's program due to the flexibility they provided in terms of loan limits and repayment schedules. While the tuition was higher than I initially expected, the program's curriculum and faculty expertise justified the expense. Pursuing this degree profoundly impacted my career trajectory, enabling me to transition into a leadership role at a rehabilitation center and fulfill my passion for community mental health advocacy."
- Michael: "Reflecting on my choice to use FAFSA for my Addiction Psychology master's degree, it was primarily because I qualified for grants that significantly offset the tuition costs. Though the cost was still a concern, managing financial aid effectively allowed me to focus fully on my studies. Earning this degree opened doors to advanced clinical roles and gave me a meaningful sense of purpose by helping individuals recover from addiction, aligning perfectly with my personal and professional goals."
Other Things You Should Know About Addiction Psychology Degrees
Most private lenders want a credit score in the mid-600s or higher, plus proof of steady income or a creditworthy cosigner. FAFSA-based federal aid does not use a credit score for eligibility, but Direct PLUS Loans require a federal credit check for adverse history.
Defaulting on loans can severely impact Addiction Psychology graduates, damaging credit scores and limiting future borrowing ability, which may hinder professional licensing or career advancement. Federal loans carry options to defer or enter income-driven repayment plans, but private loans often have less flexibility, increasing default risk. It is crucial for students to understand their repayment obligations and seek help early if they face difficulties.
- Private vs. Federal Student Loans https://www.mefa.org/article/private-vs-federal-student-loans/
- Student Loan Forgiveness for Counselors: 5 Stellar Options https://www.studentloanplanner.com/student-loan-forgiveness-counselors/
- The Pros And Cons Of Private Student Loans | Bankrate https://www.bankrate.com/loans/student-loans/pros-cons-private-student-loans/
- How Credit Affects Loans https://www.westernu.edu/financial/loan-counseling/credit/
- 8 Important Pros and Cons of Private Student Loans https://joinjuno.com/financial-literacy/student-loans/8-important-pros-and-cons-of-private-student-loans
- Federal vs. private student loans: Which borrowing option makes more sense this fall? https://www.cbsnews.com/news/federal-vs-private-student-loans-what-makes-more-sense-fall-2025/
- Private vs. PLUS Loans | COPFCU https://copfcu.studentchoice.org/resources/guides/private-vs-plus-loans/
- Financial Aid for Psychology Students https://www.onlinepsychologydegrees.com/financial-aid/
- Average Student Loan Interest Rate (2026): Federal vs Private https://educationdata.org/average-student-loan-interest-rate
- Online Master’s Degrees in Counseling Programs & Accreditation - MS in Counseling https://addiction-counselor.org/degrees/masters-counseling/