2027 FAFSA vs Private Loans for Accounting Degree Master's Students

Co-Founder and Chief Data Scientist
Choosing how to pay for an accounting master’s degree is not just a financing step; it can shape your monthly budget, career flexibility, and risk after graduation. Many students compare federal loans accessed through the FAFSA with private student loans because the two options can look similar at first: both can cover tuition and education-related expenses, and both must usually be repaid with interest.
The differences matter. Federal loans generally offer fixed rates, income-driven repayment options, deferment protections, and possible forgiveness for qualifying public service work. Private loans may help cover funding gaps, but they usually depend on credit history and may offer fewer safety nets if your income changes after graduation.
This guide explains how FAFSA-based federal loans and private loans work for accounting master’s students, including eligibility, borrowing limits, interest rates, repayment plans, credit requirements, forgiveness options, and total cost considerations. Use it to decide what to borrow first, what to avoid, and how to build a financing plan that supports your accounting career instead of limiting it.
Key Benefits of Comparing FAFSA vs Private Loans for Accounting Degree Master's Students
- FAFSA loans offer fixed interest rates and federal protections, helping accounting master's students access affordable funding with flexible repayment plans and potential loan forgiveness unavailable in private loans.
- Private loans require credit checks and often have variable rates; understanding these terms helps students weigh total costs and risks, especially for career changers entering higher-paying accounting roles.
- Knowing eligibility criteria and alternatives like scholarships prevents overborrowing; 60% of online accounting master's students use federal loans first, reducing default risk and improving financial stability post-graduation.
What Is the Difference Between FAFSA and Private Loans for Accounting Master's Students?
The core difference is that FAFSA is the application students use to access federal financial aid, while private loans are credit-based loans offered by banks, credit unions, fintech lenders, and other financial institutions. For accounting master’s students, this distinction affects eligibility, interest rates, repayment flexibility, borrower protections, and forgiveness options.
Federal aid is usually the safer first borrowing option because it is governed by federal rules and includes protections that private lenders generally do not match. Private loans can be useful when federal aid, scholarships, employer support, and savings are not enough, but they shift more risk to the borrower.
| Factor | FAFSA-Based Federal Loans | Private Student Loans |
| How students access the option | Submit the FAFSA to determine eligibility for federal aid programs such as Direct Unsubsidized Loans and Graduate PLUS Loans. | Apply directly with a lender, usually through a credit-based application. |
| Credit requirements | Direct Unsubsidized Loans do not require a credit check. Graduate PLUS Loans require a credit review. | Lenders commonly evaluate credit score, income, debt-to-income ratio, and sometimes require a cosigner. |
| Interest structure | Rates are fixed and set by the federal government. | Rates may be fixed or variable and are set by the lender based on borrower profile and market conditions. |
| Repayment protections | May include income-driven repayment, deferment, forbearance, and possible loan forgiveness. | Protections vary by lender and are usually more limited. |
| Best fit | Students who want predictable terms, federal protections, and possible forgiveness pathways. | Students with strong credit or a cosigner who need to close a remaining funding gap after using lower-risk options. |
National statistics reveal about 85% of graduate students rely on federal loans through FAFSA, reflecting its pivotal role in graduate education finance. For accounting master’s students, that does not mean federal borrowing is always enough; it means federal aid should typically be reviewed before turning to private debt.
A practical order of operations is to seek scholarships, assistantships, employer tuition support, and savings first; use federal loans next; and consider private loans only for a clearly defined remaining gap. Students comparing costs across graduate fields may also review resources such as online speech pathology masters programs to see how financing decisions differ by profession.
How Does FAFSA Eligibility Work for Accounting Master's Degree Candidates?
Accounting master’s candidates use the FAFSA to determine eligibility for federal student aid. Graduate students are treated differently from undergraduates in several important ways, especially because they are generally considered independent for FAFSA purposes. That means parental income is typically not used in the federal aid calculation.
To avoid delays, students should confirm eligibility before committing to a program budget. The main requirements include citizenship or eligible non-citizen status, enrollment in an eligible program, satisfactory academic progress, and completion of the FAFSA for the correct aid year.
- Citizenship and eligible non-citizen status: Students must be U.S. citizens or eligible non-citizens, such as permanent residents, to qualify for federal aid. International students who do not meet these rules generally need to look to institutional aid, employer support, personal funds, or private financing options.
- Enrollment in an eligible graduate program: Federal aid is tied to enrollment at an eligible institution and in an eligible program. Full-time and part-time accounting master’s students may qualify, but enrollment intensity can affect the amount and timing of aid.
- Satisfactory Academic Progress: Students must maintain satisfactory academic progress under their school’s policy. This usually includes meeting a minimum GPA requirement and completing a required percentage of attempted coursework.
- Graduate-level independent status: Graduate students are automatically considered independent on the FAFSA. This can simplify the application, but it does not mean every student receives the same aid package.
- FAFSA timing and the Student Aid Index: The FAFSA opens annually on October 1 for the upcoming academic year. Graduate students’ eligibility is determined using the Student Aid Index, which replaced the former Expected Family Contribution. Filing early can help students meet school and state priority deadlines.
About 58% of graduate students who complete FAFSA successfully receive some form of federal financial aid, demonstrating the importance of meeting these criteria. Accounting students should complete the FAFSA even if they expect to use scholarships or employer assistance, because schools may require FAFSA data to package certain types of aid.
Students weighing graduate education costs across fields may also compare long-term affordability through resources such as cheap online PhD opportunities, although doctoral funding and accounting master’s funding often operate under different assumptions.
What Federal Loan Types Are Available to Accounting Graduate Students Through FAFSA?
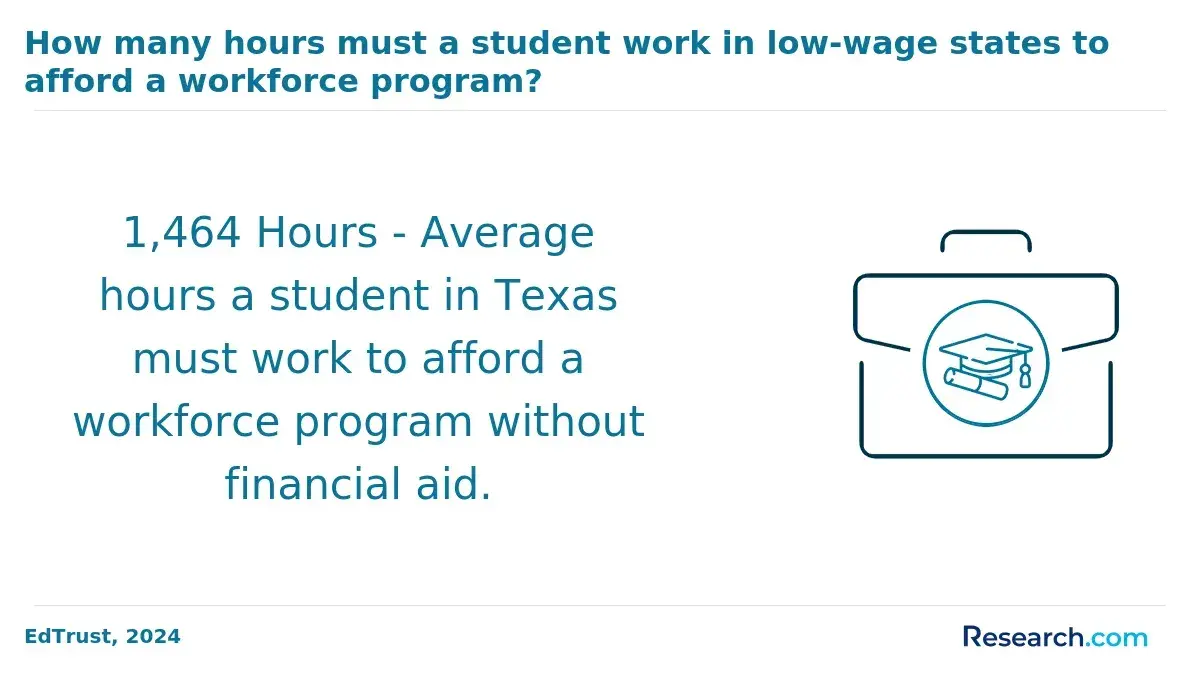
Accounting graduate students who submit the FAFSA typically focus on two federal loan options: Direct Unsubsidized Loans and Graduate PLUS Loans. The best approach is usually to use Direct Unsubsidized Loans first because they do not require a credit check and generally have lower fees than Graduate PLUS Loans. Graduate PLUS Loans can then help cover remaining school-certified costs if needed.
- Direct Unsubsidized Loans: Graduate students may borrow up to $20,500 each year with a fixed interest rate of 7.05% for the 2023-2024 academic year. An origination fee around 1.057% applies. These loans do not require a credit check, but interest accrues while the student is enrolled.
- Graduate PLUS Loans: Graduate PLUS Loans can cover remaining education costs after other aid. They have an 8.05% fixed interest rate and about a 4.228% origination fee. Borrowers must pass a credit review, but approved students may access larger amounts than the Direct Unsubsidized Loan limit allows.
- Income-driven repayment access: Both loan types may be eligible for repayment plans that adjust monthly payments based on income and family size. This can be especially useful for graduates whose first accounting role pays less than expected or who move into public or nonprofit work.
- Public Service Loan Forgiveness potential: Borrowers who work for qualifying government or nonprofit employers may be able to pursue forgiveness after 10 years of eligible payments, provided all program requirements are met.
- Deferment and forbearance options: Federal loans may allow temporary payment pauses or reductions during qualifying periods of hardship, further education, or other approved circumstances.
The key trade-off is cost versus protection. Graduate PLUS Loans can fill a larger gap, but their higher rate and fee make them more expensive than Direct Unsubsidized Loans. Before taking a Graduate PLUS Loan, accounting students should ask whether they can reduce expenses, increase scholarship funding, choose a lower-cost program, or use employer tuition benefits.
A career-changing student in an online accounting master’s program described the federal loan process as confusing at first. He used a Direct Unsubsidized Loan for core costs and then considered a Graduate PLUS Loan only after confirming his remaining balance. His main reason for staying with federal loans was not just access to funds, but the repayment flexibility if his transition into accounting took longer than expected.
FAFSA-based federal aid is often the foundation of an accounting master’s financing plan because it combines access with borrower protections. However, federal loans are still debt. Students should understand both the advantages and limits before borrowing the full amount offered.
| FAFSA-Based Aid Advantage | Why It Matters for Accounting Master’s Students |
| Fixed interest rates | Students can plan repayment with more certainty because rates do not change after disbursement. |
| No credit check for Direct Unsubsidized Loans | Students with limited credit history can still access federal graduate borrowing. |
| Income-driven repayment options | Payments may be more manageable if early-career income is lower than expected. |
| Potential forgiveness pathways | Graduates in qualifying government or nonprofit accounting roles may be able to pursue forgiveness programs. |
| FAFSA-Based Aid Limitation | How to Plan Around It |
| Borrowing caps | Direct Unsubsidized Loans may not cover the full cost of an accounting master’s program, so students may need scholarships, assistantships, savings, employer aid, or Graduate PLUS Loans. |
| Origination fees | Federal loans can cost more than the amount disbursed because fees are deducted from loan proceeds. |
| No subsidized loans for graduate students | Interest accrues while enrolled, so borrowing only what is necessary is important. |
| Aid interactions | Assistantships, fellowships, scholarships, and other aid can affect the final loan package. |
Nearly 85% of graduate students in business-related fields rely on federal loans, highlighting the importance of understanding these dynamics for accounting master’s students. The safest strategy is not to maximize borrowing automatically, but to build a realistic budget and compare the total repayment obligation with expected career outcomes.
Students focused on affordability should compare tuition, fees, delivery format, and accreditation before borrowing. Those still choosing a program can review options such as the best online business degree programs and, for accounting-specific affordability research, consider a cheapest accredited online accounting degree resource when comparing lower-cost pathways.
Private student loans are education loans issued by non-federal lenders. Accounting master’s students typically use them only when grants, scholarships, assistantships, employer benefits, savings, and federal loans do not fully cover the school-certified cost of attendance.
Unlike federal loans, private loans are underwritten. That means the lender evaluates the borrower’s credit and financial profile before deciding whether to approve the loan and what rate to offer. Students with limited income or thin credit history may need a cosigner.
- Lender types: Private loans may come from national banks, credit unions, fintech lenders, and school-affiliated lending arrangements. Each lender may use different approval standards and repayment terms.
- Approval factors: Lenders commonly review credit score, income, employment history, debt-to-income ratio, and overall repayment risk. A qualified cosigner can improve approval odds and may help the borrower receive a lower rate.
- Application and certification: Students apply with the lender, complete a credit check, and wait for the school to certify enrollment and eligible borrowing amount. Funds are generally sent to the institution rather than directly to the student.
- Repayment structures: Some lenders allow in-school deferment, interest-only payments, or immediate repayment. The right choice depends on cash flow, interest accrual, and the borrower’s ability to pay while enrolled.
- Term differences: Rates, fees, hardship options, cosigner release rules, and repayment timelines vary widely. Students should compare at least three lending offers before choosing one.
Private loans can be useful, but speed and convenience should not drive the decision. A lower advertised rate may apply only to borrowers with excellent credit, and variable-rate loans can become more expensive over time. Students should read the promissory note carefully and confirm whether the loan has deferment options, late fees, cosigner release, and any limits on hardship relief.
One accounting master’s graduate who used private loans said the most important step was involving a cosigner only after comparing lender terms. The loan closed the funding gap, but the borrower had to plan aggressively because repayment was less flexible than federal loan repayment.
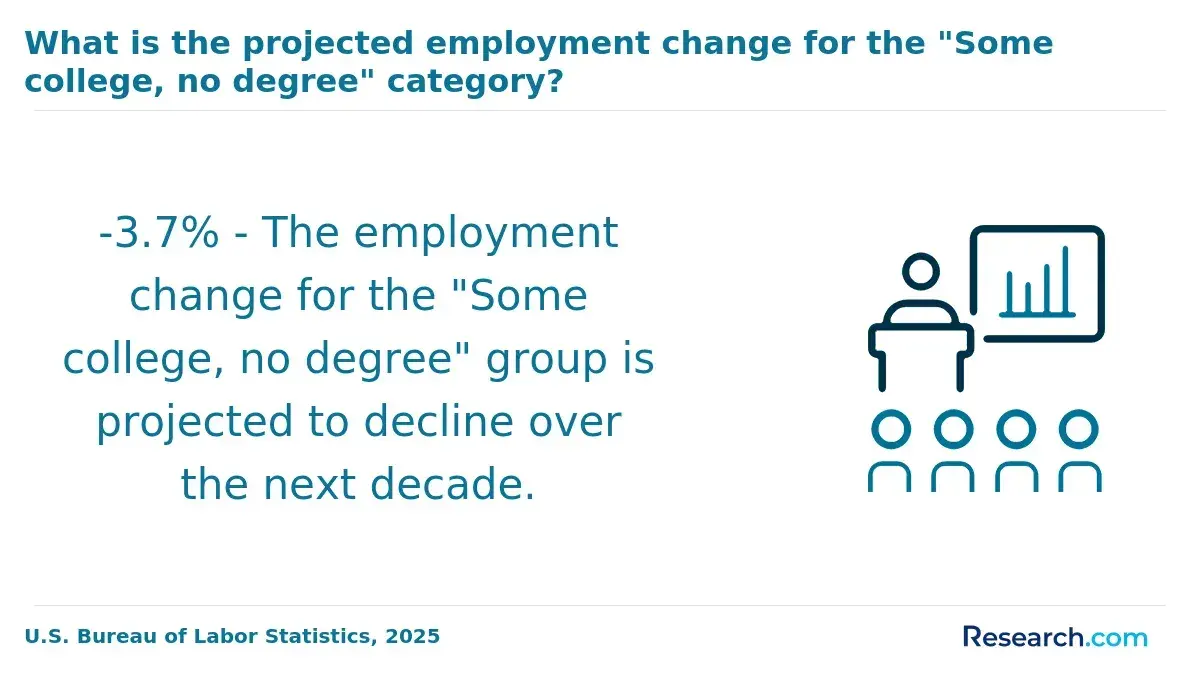
Private loans can solve a short-term funding problem, but they can also create long-term financial pressure. Accounting graduate students should view them as a gap-filling tool, not as the default way to pay for school.
| Potential Benefit | Why It Can Help |
| Higher possible borrowing amount | Some lenders may allow students to borrow up to the school-certified cost of attendance, which can help when federal loan limits are not enough. |
| Fixed or variable rate options | Borrowers may be able to choose a rate structure that matches their risk tolerance and repayment plan. |
| Fast processing | Some lenders move quickly after credit approval and school certification, which may help students facing a payment deadline. |
| Competitive rates for strong borrowers | Applicants with excellent credit and income, or a strong cosigner, may qualify for favorable terms. |
| Major Risk | Why It Matters |
| Limited repayment flexibility | Private loans usually do not offer federal income-driven repayment plans. |
| No federal forgiveness | Private loans are not eligible for federal forgiveness programs such as PSLF. |
| Credit-based approval | Students with limited credit may face denial, higher rates, or the need for a cosigner. |
| Variable-rate uncertainty | A loan that starts with a lower rate can become more expensive if rates rise. |
| Stricter consequences after default | Borrowers may have fewer hardship options and can face serious credit damage. |
Private loans make the most sense when the borrower has calculated the exact remaining need, compared multiple offers, understands the repayment schedule, and has a realistic post-graduation income plan. They are less suitable for students who are unsure about completing the program, expect a low starting salary, or may pursue nonprofit or government work where federal loan forgiveness could matter.
Federal student loans offer fixed interest rates, while private student loans may offer fixed or variable rates. This difference is crucial because accounting master’s students often borrow while their future income is still uncertain. A fixed rate provides predictability; a variable rate may start lower but can increase over time.
- Federal fixed rates: Graduate Direct Unsubsidized Loans generally carry a fixed interest rate near 7%, while Grad PLUS Loans have higher fixed rates around 8.5%, both set annually by Congress. Once a federal loan is disbursed, the rate on that loan remains fixed.
- Private variable rates: Private lenders may tie rates to benchmarks such as the Secured Overnight Financing Rate (SOFR) or the Prime Rate. Variable rates commonly range from 4% to 10%, depending on borrower profile and market conditions.
- Private fixed rates: Some private lenders also offer fixed rates. These can be easier to budget than variable rates, but approval and pricing still depend heavily on creditworthiness.
- Risk of rate changes: If SOFR or Prime rises, a private variable-rate loan can become more expensive. That risk is especially important over a typical 10-year repayment horizon.
- Need for current-rate comparison: Federal rates reset each year, and private lenders update offers frequently. Students should compare current rates, fees, repayment terms, and borrower protections before deciding.
For example, borrowing $30,000 at a 7% fixed federal rate for 10 years results in approximately $21,000 in interest, totaling about $51,000. A private loan at a mid-range variable 6% average rate may start cheaper, but possible rate hikes could push the total repayment above $55,000. The lesson is not that private loans are always more expensive, but that their long-term cost can be harder to predict.
Accounting students should compare the annual percentage rate, not just the headline interest rate. Fees, repayment timing, and capitalization can change the true cost of borrowing.
Repayment flexibility is one of the biggest differences between FAFSA-based federal loans and private student loans. Federal loans give accounting graduates several structured repayment choices, including plans based on income. Private loans usually offer fewer options and depend on the lender’s contract.
| Repayment Feature | Federal Loans Through FAFSA | Private Student Loans |
| Standard repayment | Available through a fixed repayment schedule. | Usually available through lender-defined fixed payments. |
| Graduated or extended repayment | May be available depending on loan type and balance. | Not standardized; depends on lender terms. |
| Income-driven repayment | May include Income-Based Repayment (IBR), Saving on a Valuable Education (SAVE), Income-Contingent Repayment (ICR), and Pay As You Earn (PAYE). | Generally not available. |
| Deferment and forbearance | Federal loans provide formal deferment and forbearance options, with extensions seen during the COVID-19 pandemic. | Hardship options vary by lender and may be more limited. |
| Forgiveness potential | Possible for qualifying borrowers through programs such as PSLF. | Generally not available through federal forgiveness programs. |
Nearly 70% of graduate borrowers have enrolled in federal income-driven repayment plans, highlighting their role in managing student debt. For accounting graduates, income-driven options can help during the transition from school to entry-level, mid-level, or career-changing roles.
Private loan repayment requires more caution. A lender may offer in-school deferment or interest-only payments, but after the repayment period begins, the monthly obligation may not adjust if the borrower’s income drops. This can make private loans harder to manage during job searches, CPA exam preparation periods, relocation, or career changes.
Students comparing federal loan repayment plans for accounting graduates with private student loan repayment options should prioritize free aid first, federal borrowing second, and private loans only after confirming the exact gap. Those exploring flexible online education in other disciplines may also compare programs such as an accredited online psychology degree, but repayment rules still depend on the type of loan used rather than the delivery format alone.
Yes, Public Service Loan Forgiveness can be an option for accounting master’s graduates, but only when the borrower, employer, loan type, repayment plan, and payment history meet program rules. PSLF is most relevant for graduates who plan to work in government, nonprofit, public university, or other qualifying public service roles.
- Payment requirement: Borrowers must make 120 qualifying monthly payments while enrolled in a qualifying repayment plan, typically income-driven.
- Employer requirement: Employment must be with a qualifying 501(c)(3) nonprofit organization or government employer during these payments.
- Accounting roles that may qualify: Graduates working in government agencies, public universities, nonprofit organizations, or public-sector financial offices may qualify if the employer meets PSLF rules.
- Accounting roles that generally do not qualify: Private-sector jobs, including roles at public accounting firms or private financial consultancies, generally do not qualify based on employer type.
- Loan requirement: Private student loans are ineligible for PSLF. Federal loans obtained through FAFSA are the relevant borrowing category for students who want to preserve this option.
Currently, about 25% of borrowers who enter PSLF successfully obtain loan forgiveness, indicating the program’s challenge but also its value for accounting graduates committed to public service. Students should not assume forgiveness will happen automatically. They should document qualifying employment, use the PSLF Help Tool on StudentAid.gov, and confirm that their repayment plan and loans meet program requirements.
For students planning nonprofit or government accounting careers, federal loans may be strategically preferable even if a private lender advertises a lower initial rate. For students planning private corporate accounting or public accounting firm careers, PSLF should not be the basis for the borrowing decision.
Students interested in other accelerated online pathways may review programs such as the best online construction management degree, but PSLF eligibility still depends on loan type and qualifying employment rather than the field of study alone.
Credit history can determine whether an accounting master’s student qualifies for a private loan, what interest rate they receive, and whether a cosigner is required. This is one of the clearest differences between private loans and federal Direct Unsubsidized Loans.
- Credit score expectations: Most private lenders expect a FICO score ranging from 650 to 700 or higher. Students with thin credit files may qualify for less favorable terms or may be denied.
- Income and debt review: Lenders may evaluate income, employment history, and debt-to-income ratio. A student who is enrolled full time and working less may face more scrutiny.
- Cosigner impact: A cosigner with established credit can improve approval chances and may help secure a better rate. However, the cosigner is legally responsible if the borrower fails to repay.
- Cosigner release: Some lenders offer cosigner release after consistent, on-time payments, but release is not automatic. Borrowers should confirm the exact requirements before signing.
- Federal loan contrast: Direct Unsubsidized Loans do not require a credit check. Grad PLUS Loans involve a limited adverse credit review but do not rely on traditional credit scoring models in the same way private lenders do.
Students who may need private loans should start preparing before applying. Practical steps include paying bills on time, keeping credit card balances low, avoiding unnecessary new debt, checking credit reports for errors, and comparing lenders without committing to the first offer. A slightly better rate can make a meaningful difference over a long repayment term.
The total cost of attendance, often called COA, is the school’s estimate of what it costs to attend for an academic period. It affects how much a student can borrow because federal and private loan amounts are generally tied to the school-certified COA minus other aid received.
- What COA includes: Institutions determine COA by adding tuition and fees, housing and meals, textbooks and supplies, transportation, and personal expenses. These costs vary widely among public, private, and online accounting programs.
- Federal Direct Unsubsidized Loan limit: Direct Unsubsidized Loans have a fixed annual limit of $20,500 for graduate students.
- Graduate PLUS Loan capacity: Grad PLUS Loans can cover remaining expenses up to the total COA minus any other aid received, subject to eligibility and credit review.
- Private loan certification: Private lenders typically limit borrowing to the school-certified COA after other aid. This can help students cover high-cost programs but may also increase repayment risk.
- Average cost estimates: Public accounting master’s programs average about $30,000 per year, private institutions can exceed $50,000, and online options range between $20,000 and $40,000.
COA is not the same as the amount a student should borrow. It is a ceiling, not a recommendation. Borrowing the full COA may include funds for living and personal expenses, which can significantly increase total debt. Accounting students should create a separate personal budget and borrow only what they truly need after applying scholarships, assistantships, employer aid, and savings.
Before using private loans to reach the full COA, students should calculate expected monthly repayment under federal and private scenarios. A program with lower tuition, fewer fees, or a flexible online format may reduce the need for high-risk borrowing.
What Graduates Say About Comparing FAFSA vs Private Loans for Their Accounting Master's Degree
-
: "Choosing FAFSA to finance my accounting master’s degree was a strategic decision because it offered lower interest rates compared to private loans. Although the overall cost was significant, the federal aid allowed me to manage expenses without accumulating overwhelming debt. Completing the program opened doors to senior positions in finance, and I feel more confident in both my professional capabilities and personal financial planning.
— Jordan"
-
: "The high cost of the accounting master’s program initially made me hesitant, but I decided to use private loans because they provided the flexibility I needed with repayment options. It was a challenging journey managing the debt, but the specialized knowledge I gained has been invaluable in advancing my career. Looking back, the investment was worth it as it helped me achieve long-term job security and professional satisfaction.
— Sanjay"
-
: "I opted for FAFSA because it aligned with my goal of minimizing financial stress during my studies in accounting. The cost was daunting at first, but wisely utilizing federal loans and scholarships made it manageable. This degree was a game-changer—it accelerated my path to a CPA license and gave me the credentials to pursue leadership roles, truly shaping my career and personal development.
— Divya"
Other Things You Should Know About Accounting Degrees
No. FAFSA aid covers eligible degree-seeking costs such as tuition, fees, books, and required supplies, but not a separate CPA review course unless it is billed as a required part of the master's program. Private loans may cover broader education-related expenses set by the school’s cost of attendance.
Refinancing federal loans with private lenders may lower interest rates but sacrifices federal protections like income-driven repayment and loan forgiveness. Accounting graduates with stable income and strong credit might benefit from refinancing to reduce costs, but they should carefully weigh the loss of federal benefits before deciding. Consulting a financial advisor familiar with the accounting profession's earning potential is recommended.
- Do Private Student Loans Require a Credit Check? - Experian https://www.experian.com/blogs/ask-experian/do-private-student-loans-require-credit-checks/
- Types of Financial aid for Graduate Students: Loans https://www.etbu.edu/admissions/financial-aid/types-financial-aid-graduate-students-loans
- Financial Aid and FAFSA for Master’s Degrees: What to Know https://joinjuno.com/financial-literacy/financial-aid/fafsa-masters-degree
- How Your Credit Score Affects Private Student Loan Approval - GradBridge https://gradbridge.com/how-your-credit-score-affects-private-student-loan-approval/
- Here’s how your credit score may affect your student loan approval https://www.scotiabank.com/ca/en/personal/advice-plus/features/posts.credit-scores-and-student-loans.html
- Federal Loans vs. Private Loans: Which is Better for Me? - Graduate Programs for Educators https://www.graduateprogram.org/blog/federal-loans-vs-private-loans-which-is-better-for-me/
- Public Service Loan Forgiveness (PSLF) https://www.warsawfederal.bank/resources/public-service-loan-forgiveness-pslf/
- Private student loans for international students https://www.mpowerfinancing.com/financial-empowerment/private-student-loans
- Master of Accountancy https://financialaid.mercer.edu/cost-of-attendance/graduate-and-professional/school-of-business/master-of-accountancy/
- Private Vs. Federal Student Loans: Which Is Better In 2025? | Bankrate https://www.bankrate.com/loans/student-loans/federal-vs-private-student-loans/